SBA Clarifies CRE Collateral Requirements for 7(a) Biz Acq Loans
October 29, 2026
By Bob Coleman, Publisher
Here is what matters to SBA loan brokers this week.
SBA Clarifies CRE Collateral Requirements for 7(a) Biz Acq Loans
7(a) Small Loans Up to $350,000 and SBA Express Loans Up to $500,000 Receive Commercial Real Estate Exception
SBA clarified during its October 20 quarterly 7(a) Connect Call that lenders financing business acquisitions through 7(a) Small and SBA Express loans are not required to take available equity in commercial real estate owned by borrowers, owners and guarantors.
The exception applies to 7(a) Small loans of $350,000 or less and SBA Express loans of up to $500,000 involving a change of ownership.
For SBA loan brokers, the clarification addresses a potential obstacle for business buyers who own commercial real estate unrelated to the acquisition.
The exception covers other commercial real estate solely owned by co-borrowers, direct or indirect owners of 20% or more, guarantors and supplemental guarantors. Sole ownership includes property held through an entity solely owned by those individuals.
The exception does not apply to the applicant’s project property.
SBA emphasized that lenders may still request additional commercial real estate as collateral. The agency simply does not require it under this exception.
Other applicable collateral requirements remain in effect, including those involving business assets and personal real estate.
SBA Restores Collateral Valuation Calculation
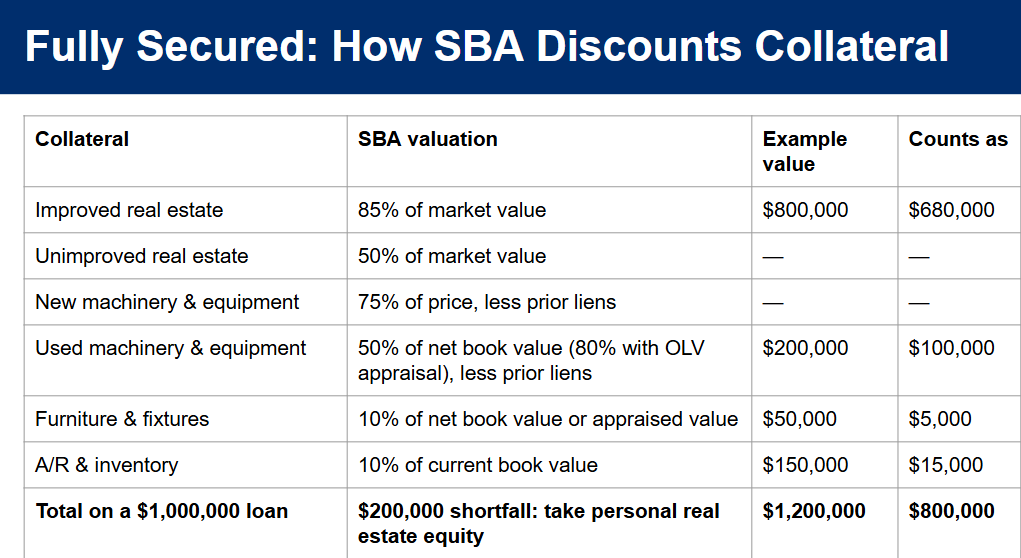
SBA also confirmed that corrected Appendix 19 of SOP 50 10 8.1 restores the fully secured collateral calculation.
The valuation discounts are not new. SBA confirmed that the percentages remain unchanged from SOP 50 10 8.
The collateral valuation limits include:
- Improved real estate: 85% of market value.
- Unimproved real estate: 50% of market value.
- New machinery and equipment: 75% of purchase price, less prior liens.
- Used machinery and equipment: 50% of net book value, or 80% with an orderly liquidation value appraisal, less prior liens.
- Furniture and fixtures: 10% of net book or appraised value.
- Accounts receivable and inventory: 10% of current book value. SBA generally requires these assets to be pledged in change-of-ownership transactions, subject to its line-of-credit exception.